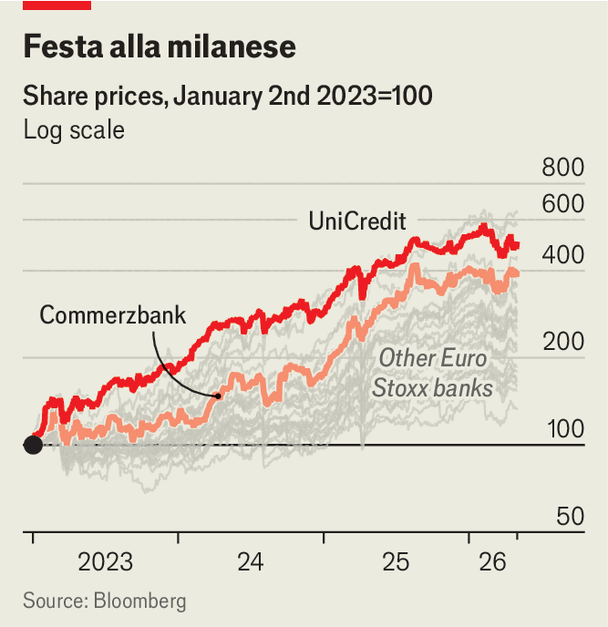
The offer was not a surprise. On May 5th UniCredit, Italy’s second-biggest bank, made a bid for all the shares it does not already own in Commerzbank, Germany’s second-biggest listed lender—as it had promised in mid-March. Until June 16th Commerzbank’s shareholders can swap(交换,置换) one share for 0.485 of UniCredit’s. It is not an enticing proposition(诱人的提议): the implied price(隐含价格) is more than 8% below Commerzbank’s closing mark(收盘价) on May 4th. The bid values the whole bank at €35bn ($41bn).
这一要约并不出人意料。5月5日,意大利第二大银行裕信银行对其尚未拥有的德国第二大上市银行德国商业银行的所有股份发出了收购要约——正如其在3月中旬所承诺的那样。到6月16日以前,德国商业银行的股东可以用1股股票换取0.485股裕信银行股票。这并非诱人的提议:隐含价格比德国商业银行5月4日的收盘价低8%以上。该收购对整家银行的估值为350亿欧元(合410亿美元)。
Why has UniCredit made such a stingy offer(吝啬的报价)? Pragmatism, its bosses say. The bid pre-empts a provision in German law that obliges a shareholder owning more than 30% of a listed company to make an offer for the rest. They envisage two scenarios for how things will play out. One is a continuation of the status quo. UniCredit, which owns just under 30% of Commerzbank, in effect controls 36% already, once total-return swaps(总收益互换) (derivative contracts that separate credit and market risk from formal ownership) are counted, says Paola Sabbione of Barclays, a British bank. The other is full control, the ultimate aim(最终目标) of Andrea Orcel, UniCredit’s chief executive.
裕信银行为何提出如此吝啬的报价?其老板们表示,这是务实之举。该收购先发制人地规避了德国法律中的一项条款,该条款规定持有上市公司30%以上股份的股东必须向其余股东发出收购要约。他们设想了两种可能的结果:一种是维持现状。英国巴克莱银行的Paola Sabbione表示,一旦计入总收益互换(一种将信用和市场风险与正式所有权分离的衍生合同),裕信银行目前持有不到30%的股份,实际上已控制36%。另一种是全面控制,这是裕信银行首席执行官Andrea Orcel的最终目标。
UniCredit already owns HypoVereinsbank (HVB), another leading German lender. With Commerzbank, it would have around 9% of the German market by revenue. The pair would complement(互补,补充) each other: Commerzbank is strong in central Germany; HVB in Bavaria, in the south and the north. So it would make sense to offer a premium(溢价) to Commerzbank shareholders instead of a discount, says Ms Sabbione.
裕信银行已拥有德国另一家领先银行HypoVereinsbank(HVB)。加上德国商业银行,其将拥有德国市场约9%的营收份额。两者将相互补充:德国商业银行在德国中部实力雄厚;HVB则在巴伐利亚以及德国南北部占优。因此,巴克莱的Sabbione表示,向德国商业银行股东提供溢价而非折价才合理。