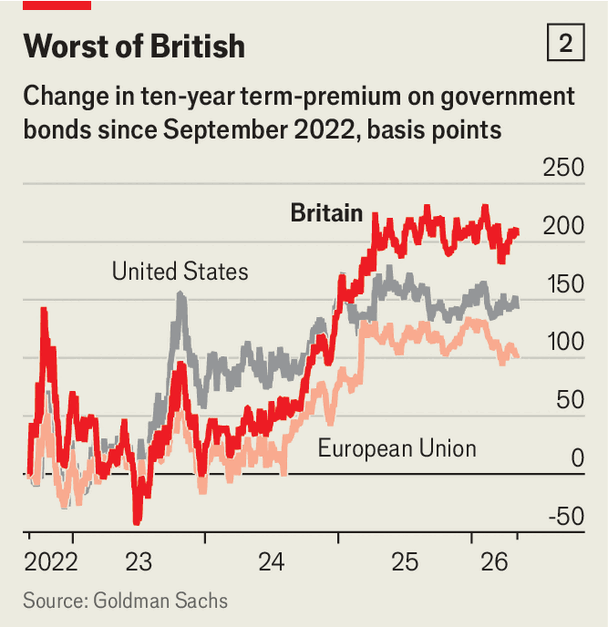
Labour’s drubbing(惨败) in the local elections on May 7th has started two crucial contests. The first, to replace Sir Keir Starmer as prime minister, is already getting messy. The second, between leadership hopefuls and the bond market, could get ugly. Andy Burnham, one would-be prime minister, has moaned about Britain being “in hock to(受制于) the bond markets”. One MP supporting Mr Burnham said the bond markets would “have to fall in line(服从)” if he were elected. Investors in gilts(金边债券) (British government bonds) have hit back. For ten-year gilts the yield(收益率) (the rate the government pays to borrow) rose by nearly 0.2 percentage points on May 11th-12th alone.
工党在5月7日地方选举中的惨败开启了两场关键竞争。第一场是取代基尔·斯塔默爵士成为首相,已经变得混乱。第二场则是领袖竞选者与债券市场之间的较量,可能会变得难看。潜在首相候选人之一安迪·伯纳姆抱怨英国“受制于债券市场”。一名支持伯纳姆的议员表示,如果他当选,债券市场将“必须服从”。金边债券(英国政府债券)的投资者进行了反击。仅5月11日至12日,十年期金边债券的收益率(政府借款的利率)就上涨了近0.2个百分点。
Many Labour politicians see the gilt market as a bully(欺凌者) that will back down(退缩) if you stand up to it. In reality, the government spends more than it taxes and must persuade investors to fund the gap. Those investors ask two questions: how risky is British government debt? And, adjusting for that risk, can they get a better return elsewhere? The answers are largely determined by global forces or structural problems with the British economy that cannot be magicked away(消失). No leadership hopeful can fully shake off the gilt market’s whims. But fiscal incontinence(财政失控) makes matters worse; avoiding it is the best way to escape the market’s wrath.
许多工党政客将金边债券市场视为一个欺软怕硬者,认为只要勇敢面对它就会退缩。实际上,政府支出超过税收,必须说服投资者填补缺口。这些投资者会问两个问题:英国政府债务的风险有多大?以及,在考虑风险调整后,他们能否在其他地方获得更好的回报?答案很大程度上由全球力量或英国经济的结构性问题决定,这些问题无法凭空消失。没有哪位领袖候选人能完全摆脱金边债券市场反复无常的影响。但财政失控会使情况更糟;避免财政失控才是逃避市场怒火的最佳途径。
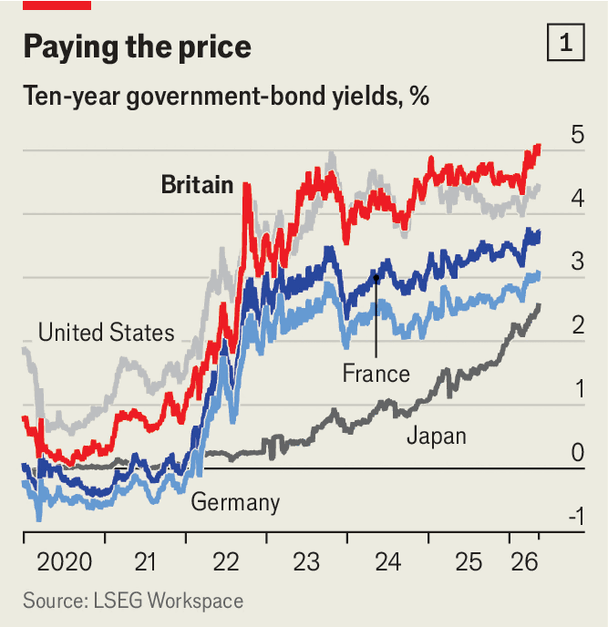
Since the Iran war(①本文中'伊朗战争'是一个假设性或未来冲...) began yields on ten-year gilts have leapt(急剧上升) from 4.2% to a high of 5.2% in late April. This trajectory(轨迹) is a global phenomenon; sharply rising energy prices are increasing inflation everywhere. Markets expect central banks will need to raise interest rates to bring price rises back to target. But Britain is unusual in how badly it has been damaged. The country’s yields, already the highest in the G7(七国集团) group of large rich countries, have seen the biggest jump since the Iran war began—double that of Germany (see chart 1).
自伊朗战争开始以来,十年期金边债券的收益率从4.2%跃升至4月底的5.2%高位。这一轨迹是一种全球现象;能源价格急剧上涨正在推高各地的通胀。市场预计央行将需要提高利率以将物价涨幅拉回目标水平。但英国受损程度异常严重。该国收益率本就已是七国集团中最高,自伊朗战争以来涨幅最大——是德国的两倍(见图表1)。
Loss of Truss
特拉斯之失