AROUND THE time The Beatles were setting the standard(树立标准) for pop music, a group of academics—many of them future rock stars(摇滚明星(比喻)) of investment—were doing the same in finance. They developed the Capital Asset Pricing Model(资本资产定价模型) (CAPM), which estimates the return investors should expect for taking on risks(承担风险).
大约在披头士乐队为流行音乐树立标准之时,一群学者——其中许多人是未来的投资界巨星——也在金融领域做着同样的事。他们开发了资本资产定价模型(CAPM),该模型估计投资者因承担风险而应获得的回报。
To work out(计算出,弄明白) that return on risk, they realised, investors would need to know what a riskless investment(无风险投资) earned. An economist named William Sharpe aimed to find a “pure interest rate”. Six decades later the CAPM drives trillions of dollars of investment decisions; the “Sharpe ratio(夏普比率)”, measuring risk-adjusted performance, is still used everywhere in finance. The supposedly riskless asset underlying(潜在的,基础的) these influential calculations is almost always a Treasury security.
要计算出风险回报,他们意识到投资者需要知道无风险投资的收益。一位名叫威廉·夏普的经济学家旨在找到一种“纯利率”。六十年后,CAPM驱动着数万亿美元的投资决策;衡量风险调整后表现的“夏普比率”仍在金融领域无处不在。支撑这些有影响力计算的所谓无风险资产几乎总是美国国债。
What happens, then, if Treasuries are no longer deemed(被视为) riskless? A lot more than the theory underpinning portfolio construction would be in jeopardy(处于危险中). Treasury-market prices are to investors like water to a fish.(国债市场价格对投资者而言,如同水对鱼一样。) The assets are so fundamental to global finance that it is tough to imagine a world without them. It would be a world with higher interest rates, greater uncertainty and more risk. It would be more dangerous and difficult to navigate(驾驭,顺利应对) for investors and taxpayers not just in America, but in the rest of the world, too.
那么,如果美国国债不再被视为无风险,会发生什么?岌岌可危的远不止是支撑投资组合构建的理论。国债市场价格对投资者而言,就像水对鱼一样。这些资产对全球金融如此基础,以至于难以想象一个没有它们的世界。那将是一个利率更高、不确定性更大、风险更多的世界。对投资者和纳税人而言,不仅在美国,而且在世界其他地区,都将更加危险和难以驾驭。
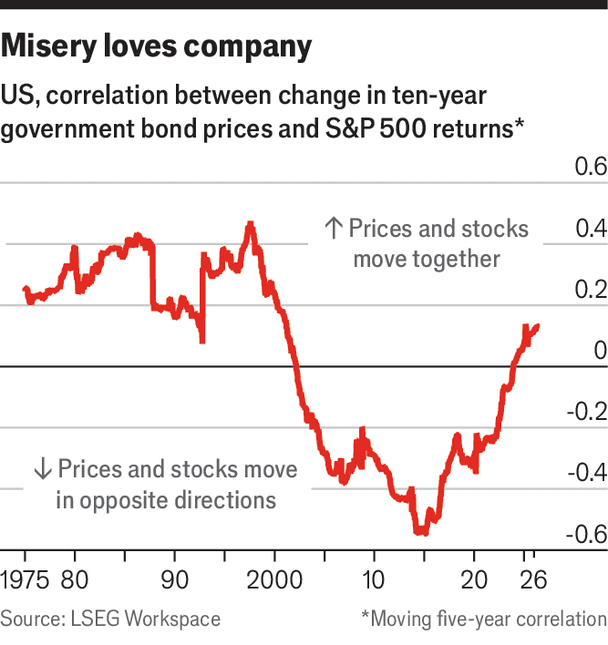
Yield to no one
不让步于任何人