THE SCALE of the Treasury market is mind-boggling(令人难以置信的). Some $1trn in securities change hands(易手,转手) each day. Trillions more are used as collateral(抵押品) for short-term loans. Financial institutions of all stripes(各种类型的) are involved: banks, central banks, high-speed traders, insurers, endowments(捐赠基金), pension funds, hedge funds and so on.
美国国债市场的规模令人难以置信。每天有约1万亿美元的证券易手。还有数万亿美元被用作短期贷款的抵押品。各种类型的金融机构都参与其中:银行、中央银行、高速交易商、保险公司、捐赠基金、养老基金、对冲基金等等。
It used to be that banks were the main facilitators(推动者,促进者) of all this, acting as “market-makers(做市商)” for other financial firms. As recently as 2009 about half of Treasuries with maturities(到期期限) of a year or more were bought at auction by the brokerage arms(经纪部门) of investment banks, which then sold them on(转卖它们). But new regulations(监管规定) introduced after the financial crisis diminished banks’ role as intermediaries(中介) in the Treasury market, by requiring them to fund themselves with more capital(用更多资本为自身融资) to underpin(支撑,支持) such mundane(平凡的,普通的) transactions. Dealer banks now buy just 12% of Treasuries maturing in over a year at auction.
过去,银行是这一切的主要推动者,充当其他金融公司的“做市商”。就在2009年,一年期以上国债中约有一半在拍卖中被投资银行的经纪部门购买,然后转卖。但金融危机后引入的新监管规定削弱了银行在国债市场的中介作用,要求它们用更多资本为自身融资,以支撑这些普通交易。如今,交易商银行在拍卖中仅购买了一年期以上国债的12%。
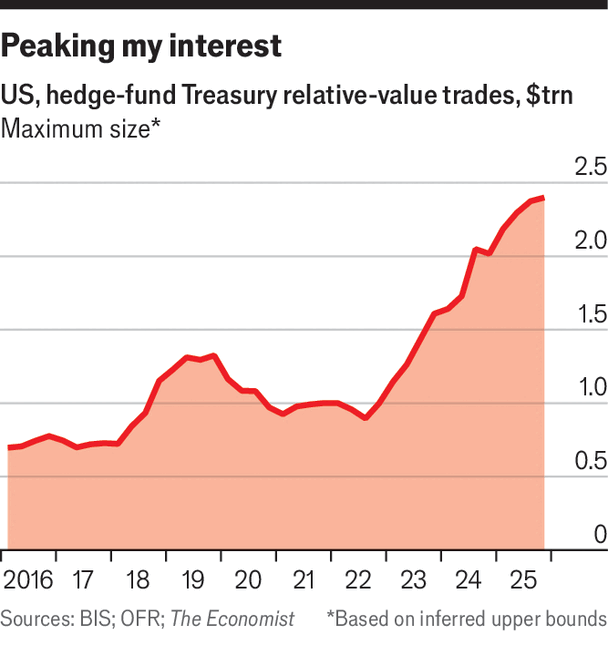
Another prolific(多产的,大量的) buyer has helped to fill the void(填补空缺): hedge funds. These try to profit from Treasuries in lots of ways, but one approach, called relative value, causes particular consternation(惊恐,惊愕). This involves exploiting tiny discrepancies(差异,不一致) in the prices of similar assets which will converge(收敛,趋同) over time. Because the differences in price are minuscule(极小的), so are the profits. To make such trades worthwhile, hedge funds pursue them at huge scale using borrowed cash. To that end, they hold $2.4trn of long exposure(多头敞口) to Treasuries—bets that the bonds will rise in value—in the form of the securities themselves and derivatives (see chart).
另一种多产买家填补了这一空缺:对冲基金。它们试图通过多种方式从国债中获利,但有一种称为相对价值的方法尤其令人担忧。这涉及利用类似资产价格之间的微小差异,这些差异会随时间收敛。由于价格差异极小,利润也极小。为了使此类交易有利可图,对冲基金使用借来的现金大规模进行交易。为此,他们以证券本身和衍生品的形式持有2.4万亿美元的美债多头敞口——押注债券价值上涨(见图表)。
Don’t get squashed
别被压扁